
by Eurolng.com Staff
Gdańsk FSRU: what it means for the small-scale LNG market
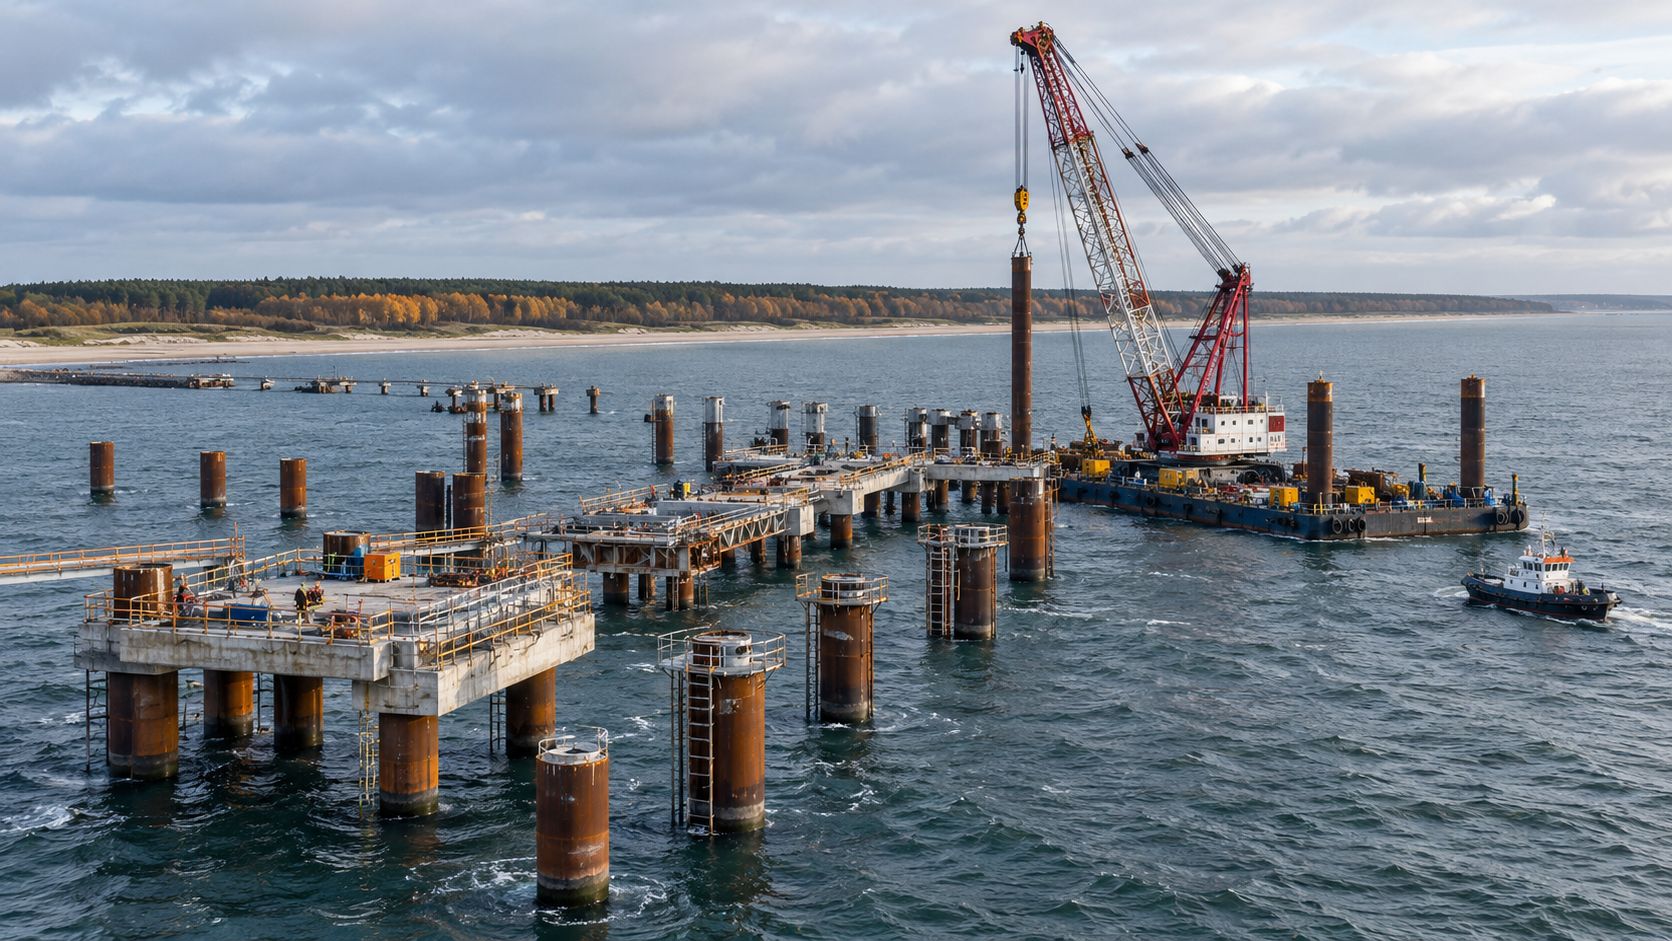
Gaz-System completes key quay construction stage — start in 2028
In October 2026 Polish state-owned company Gaz-System announced the completion of driving more than 500 piles for the quay of the future floating LNG terminal (FSRU) in the Gulf of Gdańsk. This is one of the most visible stages in building Poland’s second maritime entry point for gas imports. Below is what has been done, when the terminal will start and how it will affect the small-scale LNG market.
1. What is being built and when it starts
The project is a floating FSRU terminal in the Gulf of Gdańsk (FSRU Programme). A permanently moored FSRU unit (working name Solidarity) will receive LNG from carriers, store it and regasify it into the grid.
- Capacity of the first unit: 6.1 bcm of gas per year.
- Storage on the FSRU: about 170,000 m³ of LNG.
- Commercial start: early 2028 (technological commissioning at the turn of 2027/2028).
- Full capacity of the first FSRU has already been booked by Orlen.
- A second FSRU in the same bay is planned for around 2030 (potentially another ~6 bcm).
In parallel the onshore Gdańsk–Gustorzyn pipeline (~250 km) is nearly complete. The microtunnel under the beach and dunes for the offshore section has already been bored. The FSRU vessel is being fitted out at a shipyard in Ulsan, South Korea.
2. Current ssLNG base in Poland — Świnoujście
For now the main source of small-scale LNG is the Świnoujście terminal. In 2026 Gaz-System commissioned the fourth truck-loading bay: capacity rose to roughly 60 tankers per day and about 360,000 t of LNG per year. Since the service started more than 57,000 tankers have left the terminal (over 2.3 million m³ of LNG). This is the real infrastructure of Polish ssLNG today.
The Gdańsk FSRU was designed primarily as a large-scale entry into the national transmission system, not as a direct replacement or duplicate of truck loading. There are no public announcements yet of full truck-loading bays on the FSRU itself.
3. What the Gdańsk FSRU gives the ssLNG market
Even without its own truck-loading facilities the project changes the picture for the small-scale segment:
More molecules in the system. An extra 6.1 bcm per year from 2028 (and potentially as much again after 2030) increases overall LNG/gas availability in northern and central Poland. This reduces shortage risks and can soften regional spreads.
Logistics further north. For consumers in northern and north-eastern Poland, and for deliveries toward the Baltics and neighbouring markets, a second major hub near Gdańsk appears. Some volumes currently pulled only from Świnoujście could in theory be served over shorter distances.
Potential for additional services. An FSRU can by design provide additional services (reloading to smaller vessels, bunkering, and in the longer term truck loading). This is not yet fixed as a mandatory element of the first phase, but the quay infrastructure creates the technical possibility for further ssLNG service development.
Regional hub. Poland strengthens its role as an exporter/transit country for gas to Ukraine, Slovakia and Hungary. Part of that demand can be met by small-scale logistics (road tankers, ISO containers), especially where there is no direct pipeline.
Key figures
| Parameter | Value |
|---|---|
| FSRU-1 capacity (Gdańsk) | 6.1 bcm/year |
| Commercial start | early 2028 |
| Capacity booking | Orlen — 100% |
| FSRU-2 (plan) | ~2030, another ~6 bcm |
| Truck loading (Świnoujście) | up to 60 trucks/day, ~360 kt/year |
4. Takeaways for ssLNG suppliers and buyers
The Gdańsk FSRU is primarily a large-scale energy-security project. For the small-scale LNG market it does not replace Świnoujście, but it strengthens the overall balance, improves logistics in northern Poland and creates a platform for possible future ssLNG services (reloading, bunkering, potential truck loading). For ssLNG buyers in Poland and neighbouring countries this means more available molecules after 2028 and competition between two maritime entry points. For suppliers from the Baltics and Central Europe it adds a new reference on the map: next to the already operating truck loading in Świnoujście a second major hub appears near Gdańsk.