Menu
  • Topics
    • European LNG market
    • Small-scale LNG
    • Green methane
  • About Us
  • Traderoom
  • Log In
  • Join today
  • Terms and Conditions
  • Privacy Policy
  • Cookie Settings
Product has been added to your cart.

LNG and CNG trucks in Europe: who leads — Scania, Volvo or Iveco?
Home
Topics
Small-scale LNG
LNG and CNG trucks in Europe: who leads — Scania, Volvo or Iveco?
26 Sep at 07:32

by Eurolng.com Staff

LNG and CNG trucks in Europe

Comparison of Germany, France, Italy and the Netherlands

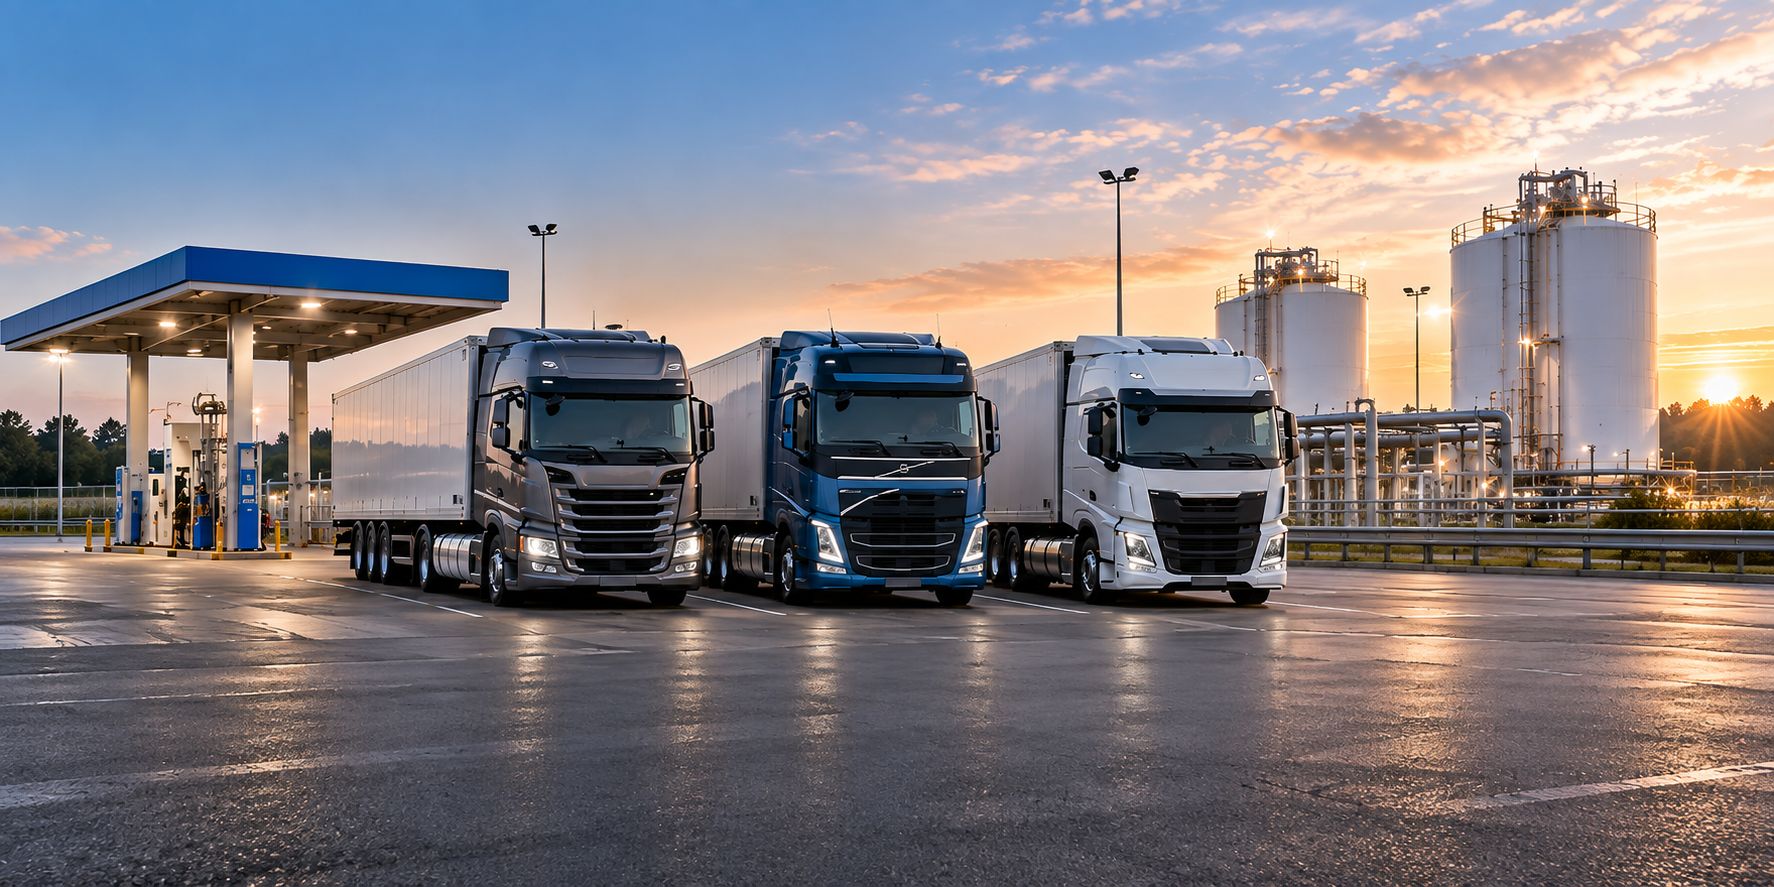
The European gas truck market remains a niche but resilient segment. After the downturn caused by the energy crisis, sales have partially recovered. The picture differs sharply by country and by gas type (LNG vs CNG). Below is the current ranking of the three key manufacturers: Scania, Volvo and Iveco.

1. Country comparison (2025)

Brand Germany France Italy Netherlands
Iveco Present, weaker in pure LNG GNV leader Clear market leader (~30%) ~8% of LNG
Volvo LNG leader, major orders Strong in GNL tractors 3rd–4th place, gas present Leader (~60% of LNG)
Scania Active in LNG/CNG Solid GNV volumes 2nd in overall market ~33% of LNG

Netherlands data cover LNG registrations only in 2025 (just 88 vehicles). Other countries reflect the combined GNV/LNG/CNG segment.

2. Germany

  • Almost 100% of fuel sold at stations is Bio-LNG (98.5% in 2025).
  • More than 199 LNG filling stations; fuel sales reached 166.5 kt (slight decline).
  • Major signal: 500 Volvo FH Aero LNG ordered by REINERT Logistics.
  • Main constraint: removal of the Maut discount from 2024.

3. France

  • 1,470 heavy GNV truck registrations in 2025 (market share ~3.3%).
  • Iveco is the clear leader. Volvo is strong in GNL tractors; Scania posts steady volumes.
  • More dynamic in new vehicle numbers than Germany.

4. Italy

  • Historically one of Europe’s largest gas truck fleets (>3,000 units in circulation).
  • In 2025 gas registrations fell by about 31%. Electric vehicles overtook gas in new sales for the first time.
  • Iveco keeps ~30% of the overall truck market and remains the main player in the methane segment.

5. Netherlands

  • Only 88 LNG trucks registered in 2025.
  • Clear ranking: Volvo (~60%) → Scania (~33%) → Iveco (~8%).

6. Conclusion

  • Long-haul LNG: Volvo leads (especially Germany and the Netherlands).
  • CNG and medium-duty: Iveco is strongest (France and Italy).
  • Scania holds a balanced position across all key markets.

Gas trucks remain a practical option for hauliers, particularly when running on Bio-LNG or Bio-CNG. Further growth will depend on road tolls, biofuel prices and regulatory support.

Previous Post
Bio-LNG growth in Belgium: Zeebrugge as a North-West European hub
Next Post
Small-Scale LNG in Latvia: market, players and 2025 analysis

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Fill out this field
Fill out this field
Please enter a valid email address.
You need to agree with the terms to proceed

Latest Articles

  • QATAR AND HORMUZ: OCTOBER LNG LOADINGS HIT HIGHEST LEVEL SINCE THE CONFLICT BEGAN November 12, 2026
  • SMALL-SCALE LNG MARKET UPDATE: MID-NOVEMBER 2026 November 12, 2026
  • TTF VS HENRY HUB: WHY THE EUROPEAN PREMIUM PERSISTS November 12, 2026
  • EEX launches EU ETS2 auction and spot market from 18 January 2027 November 10, 2026
  • What would have to change for Europe to stop paying more for LNG November 9, 2026

We make 𝐜𝐥𝐞𝐚𝐧 𝐞𝐧𝐞𝐫𝐠𝐲 𝐚𝐧 𝐞𝐚𝐬𝐲 𝐜𝐡𝐨𝐢𝐜𝐞 𝐟𝐨𝐫 𝐛𝐮𝐬𝐢𝐧𝐞𝐬𝐬𝐞𝐬 𝐚𝐜𝐫𝐨𝐬𝐬 𝐄𝐮𝐫𝐨𝐩𝐞.

European LNG Intelligence
Peterburi tee 2F, Tallinn, ESTONIA

info@eurolng.com
Topics
European LNG market
Green methane
Small-scale LNG
  • Topics
  • About Us
  • Traderoom
  • Log In
  • Join today
  • Terms and Conditions
  • Privacy Policy
  • Cookie Settings
Cookie Policy (EU)

2026 © All rights reserved

Website design
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}