
by Eurolng.com Staff
Small-scale LNG market development in Italy
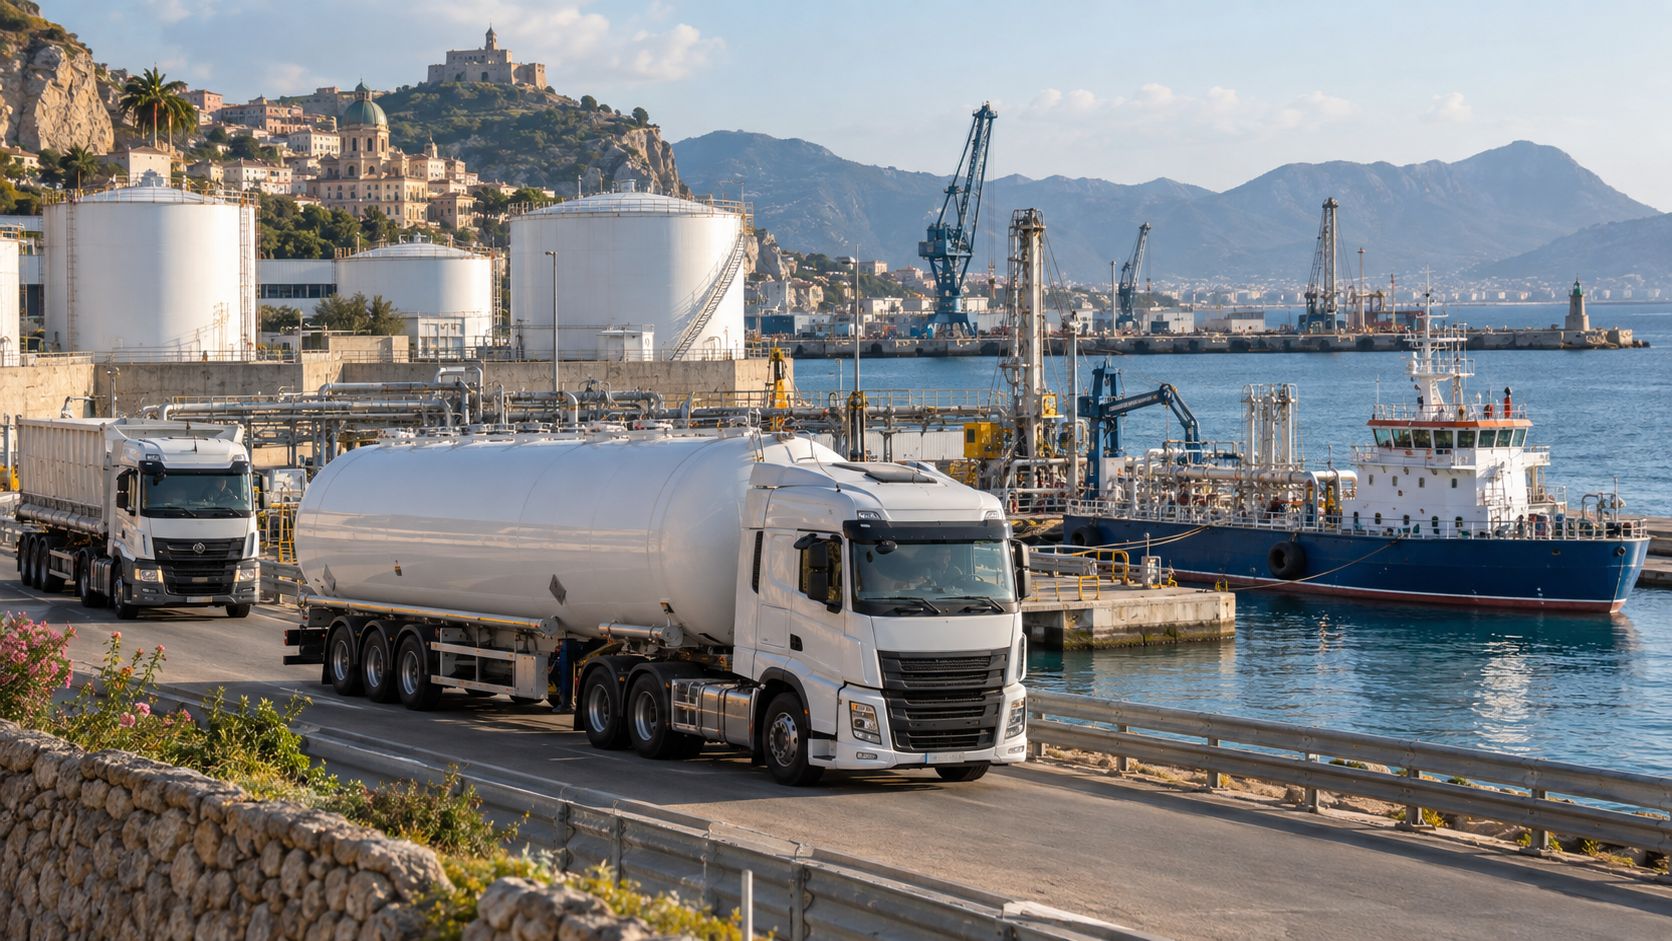
Road transport, bunkering and industry — volumes, players and outlook
Italy is one of the largest small-scale LNG markets in Southern Europe. The country combines a developed network of truck filling stations, a growing maritime bunkering segment and access to major regasification terminals. The bulk of volume still goes to road transport, but since 2025–2026 ship bunkering has been expanding rapidly.
1. Market volumes
According to industry sources (Assocostieri, Bip Consulting and others):
- 2024: around 160–208 thousand tonnes;
- 2025: approximately 220–230 thousand tonnes (growth continues, but at a moderate pace).
2. Demand structure by sector
| Sector | Share | Comment |
|---|---|---|
| Road transport (trucks) | ~80–85 % | ~180 LNG/L-CNG stations; the main market driver |
| Ship bunkering | Growing | Genoa, Livorno, Naples, Civitavecchia; regular STS operations since 2025–2026 |
| Industry / off-grid | Remainder | Satellites, Sardinia, sites without pipeline access |
3. Road transport
The filling-station network is concentrated in the Centre and North of the country (~180 LNG/L-CNG stations in 2025). Network expansion has slowed (about +3 % in 2025 versus +10–11 % the year before). The LNG truck fleet is growing only modestly — around 300 new vehicles were registered in 2024.
A key risk is the ageing of the first generation of LNG trucks and a possible return of some operators to diesel without additional incentives.
4. Ship bunkering
Since 2025–2026 the segment has been moving from pilot operations to regular service. Key developments:
- OLT Offshore LNG Toscana (Livorno) launched a commercial small-scale service;
- Axpo operates bunker vessels (Green Pearl and others) and carries out ship-to-ship / ship-to-truck operations;
- first Bio-LNG bunkering operations (including in Genoa);
- small-scale slot auctions at terminals (2025) confirmed solid demand.
5. Main sellers and operators
| Player | Role |
|---|---|
| Eni | Major LNG supplier, logistics integration, bunkering |
| Edison | Ravenna depot (~51 % of road loadings) |
| Snam / OLT Toscana | FSRU Livorno — commercial small-scale service |
| Axpo | Bunkering (Green Pearl etc.), STS and ship-to-truck |
| Gas and Heat | Joint projects on bunker vessels |
| Molgas, Shell, TotalEnergies | International supply and operations |
6. Logistics
- Ravenna (Edison) is the key hub for road loadings.
- A significant share of supply still comes from Fos/Marseille in France (~37 % of road volumes).
- Oristano (Sardinia) supplies island networks.
- OLT Toscana and new projects (including Vado Ligure) expand small-scale capacity.
7. Outlook
- Road transport will remain the demand base, but growth will depend on support schemes and fleet renewal.
- Bunkering is the main growth driver for 2026–2030 (FuelEU Maritime, Mediterranean SECA).
- Bio-LNG is already entering the market; certification and availability will determine the premium.
8. Conclusion
Small-scale LNG in Italy is a mature road-transport market (~80–85 % of volume) and a fast-growing bunkering segment. 2025 volume is estimated at 220–230 thousand tonnes. Key players are Eni, Edison, Snam/OLT and Axpo. For suppliers from other European regions both road deliveries and participation in the emerging Mediterranean bunkering chain are of interest.